This article provides general information to support better planning. Individual medical decisions and fitness for travel require assessment by qualified treating professionals.
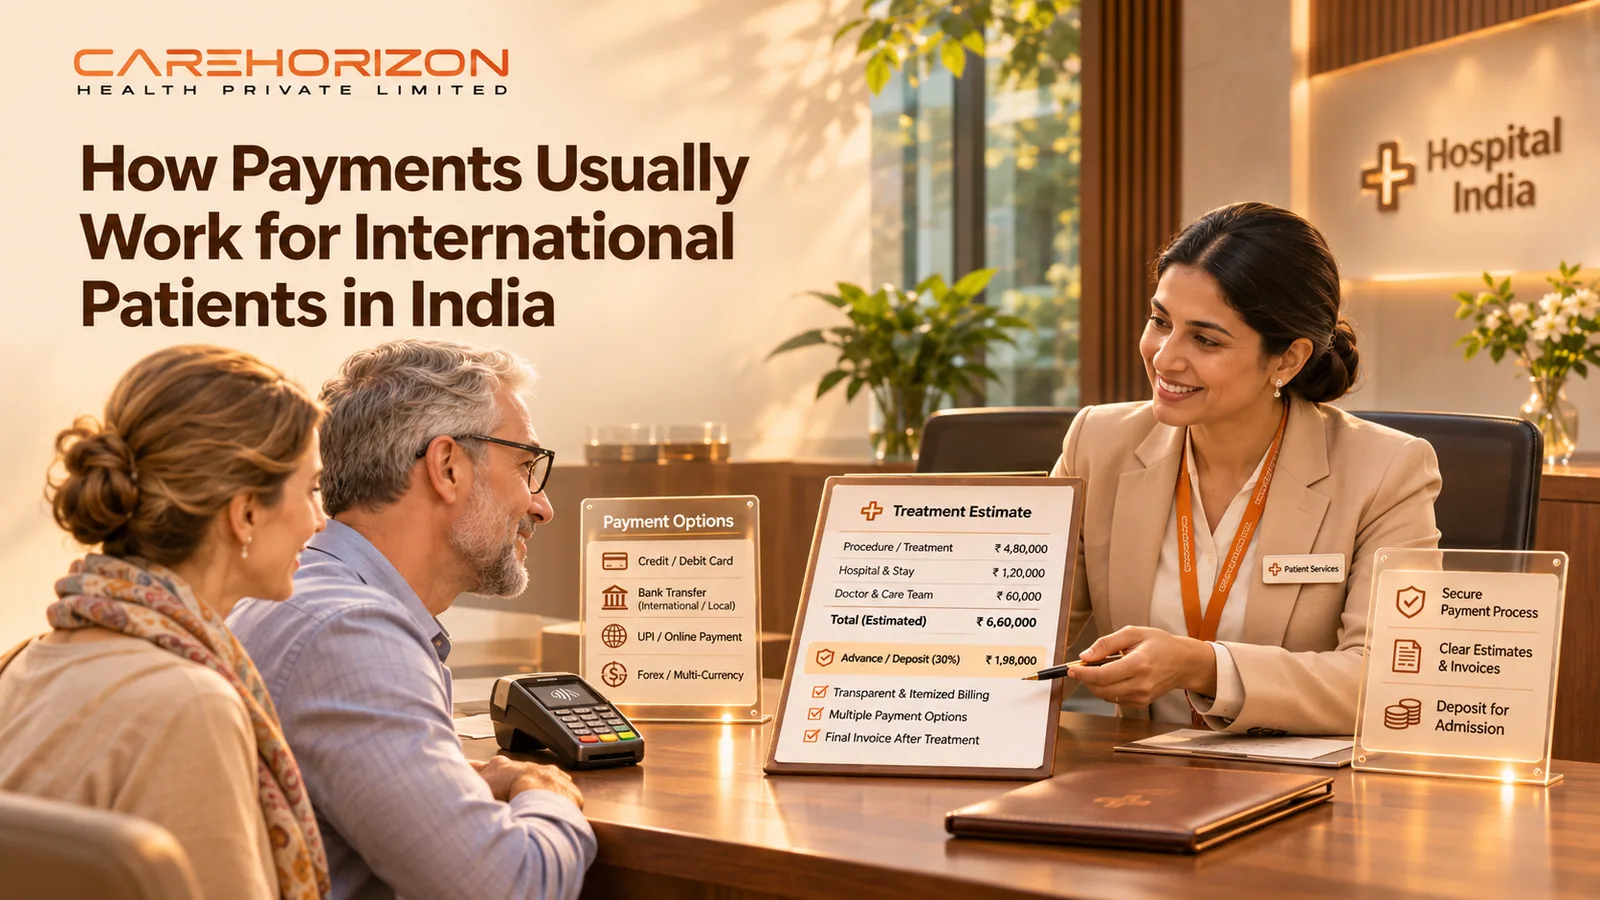
A family planning treatment in India often receives several financial requests before the patient travels: a preliminary estimate, a possible appointment or admission deposit, payment instructions and sometimes a request for information about insurance. Once treatment starts, additional invoices may follow. If the family is paying from overseas, exchange rates, bank fees and settlement times add another layer of complexity.
There is no single payment system used by every Indian hospital. Some institutions accept international bank transfers or major cards, some use online portals, and payment requirements can depend on treatment, hospital policy, country of origin and insurer arrangements. The CDC's India travel guidance notes that major hospitals in larger cities commonly accept major credit cards, while payment options elsewhere may differ. Patients should always check with the specific institution.
This article explains how international patient payment in India generally unfolds, from requesting a written treatment estimate to making a deposit, converting currency, paying hospital bills and resolving refunds. It also explains what medical travel coordinators can clarify without taking responsibility for a hospital's charges. For the wider treatment journey, see Carehorizon's information on treatment in India.
The Typical Payment Journey in Seven Stages
A common planning sequence begins with a clinical enquiry and preliminary hospital estimate. The family then clarifies the proposed care and payment terms, checks insurance or sponsorship, verifies the payment recipient and sends any required deposit. During admission, the hospital records actual services and may ask for additional funds. At discharge, the billing department prepares the final invoice and applies deposits or approved coverage.
A refund or balance payment may follow after reconciliation. Hospital policies, currency arrangements and timing vary, so treat this as an illustration rather than a universal rule. Each financial milestone should be documented in writing.
The crucial distinction is between the projected cost before treatment and the actual amount due after care has been provided. Families should ask what is fixed, what is provisional and who can authorise or explain changes.
First Understand the Hospital's Treatment Estimate
An estimate may cover a consultation, procedure, inpatient stay or course of treatment. It may be based on reports sent from abroad and remain conditional on an examination, additional imaging or pathology review after arrival.
Look for the exact hospital and campus, proposed care, currency, itemised or package scope, expected duration, validity and notable exclusions. If the estimate does not identify the clinical plan, ask for the reviewing specialist's input before focusing on the amount.
The guide to understanding hospital estimates explains common inclusions, exclusions and uncertainties.
Is a Treatment Estimate the Same as a Final Bill?
No. An estimate describes anticipated charges under stated assumptions. The final invoice ordinarily reflects the actual investigations, professional services, treatments, medicines, accommodation and other services billed under the hospital's terms.
Changes may arise from a revised diagnosis, extra tests, medical complications, longer admission, room-category changes or another clinical recommendation. A hospital should explain important revisions, but a legitimate change is not proof of overcharging or fraud.
Ask who will communicate financial updates and how the patient or authorised representative can review them before discharge.
Why Hospitals May Request an Advance Deposit
A hospital may require an advance payment to secure a booking, cover anticipated admission charges or comply with its policy for self-funded treatment. The timing and amount vary, and not every enquiry requires a deposit.
Before paying, obtain an official request that identifies the hospital or lawful collecting entity, case reference, amount, currency, due date and applicable terms. A deposit should be supported by a receipt or transaction acknowledgment.
Ask whether the payment is refundable, transferable to another date or credited against the final invoice. Never assume a deposit guarantees that a particular surgery will happen regardless of clinical findings.
Appointment Fee, Admission Deposit and Treatment Payment
These labels can refer to different transactions. A consultation fee may pay for a doctor's review or appointment. An admission deposit may be an advance against expected inpatient charges. A scheduled treatment payment may relate to an agreed package or particular stage.
The patient should know which transaction is being requested and what happens if the proposed treatment changes. A consultation payment does not automatically mean the hospital has accepted the patient for surgery.
Request separate documentation if there is also a third-party medical coordination or travel service fee. Keeping payees and services clear prevents confusion later.
Which Currency Will the Hospital Quote?
Many Indian hospital bills and tariff schedules are denominated in Indian rupees, but the format used for an international patient may vary. Some hospitals provide an indicative equivalent in another currency, while others communicate the rupee amount to be paid through an approved method.
Ask for the invoice currency, the settlement currency accepted and how any foreign-currency equivalent is calculated. A converted figure shown for convenience should not be mistaken for a guaranteed exchange rate.
Never assume a quote in US dollars or another currency will be settled at the same rate weeks later. Verify the contractual terms with the hospital and the payment provider.
How Currency Exchange Changes the Amount Paid
When a patient pays from an account in a foreign currency, the bank or payment provider may convert funds into the hospital's settlement currency. The applied exchange rate, conversion spread, service charge and correspondent-bank deductions can affect the total debited or received.
These charges are not necessarily imposed by the hospital. The sending bank and any intermediary or receiving bank may have their own terms, and a card network may apply a different conversion method.
For budgeting, ask both parties what currency and amount the hospital must receive, and whether bank fees should be paid separately. A rate displayed on a search engine is not a binding rate for a medical payment.
Example: Why an Indicative Exchange Rate Is Not Your Final Cost
Imagine that a hospital estimate is INR 500,000. The family may calculate an approximate foreign-currency equivalent using a published reference rate. But the bank may apply a different executable exchange rate and charge transfer fees.
If the hospital needs to receive INR 500,000 net, the payer must understand whether the transfer instruction or service charges might result in a lower amount being credited. If the sending currency moves between estimate and payment, the required foreign-currency outlay may also change.
This is an illustrative scenario, not a live rate quote or an assertion that a particular bank or hospital charges a specific fee.
International Bank Transfers
Some hospitals provide official bank details for an overseas wire transfer. Ask the receiving hospital which beneficiary information, account identifiers, bank address, SWIFT or other routing details and reference text are required.
Bank processing times and documentation requirements differ by provider and jurisdiction. A sending bank may request the invoice or purpose of payment; the receiving institution may need to match the incoming amount to the patient.
Use bank details verified independently through the hospital's official contact channel, especially if instructions change at the last moment. Retain the transfer confirmation and ask the hospital to acknowledge receipt.
What if the Payment Arrives Short?
The amount that reaches the hospital may differ from the amount sent because of currency conversion and bank charges. A hospital may then ask for the shortfall or place the payment on hold until it can be reconciled.
Before initiating the transfer, clarify which charges are borne by the sender, which deductions may occur en route and how a short payment is handled. Do not assume the bank's confirmation proves that the hospital received the exact invoice amount.
If there is a discrepancy, ask the sender bank for payment tracking information and the hospital for the actual credited amount. Avoid making a duplicate payment before the first transfer has been traced.
Paying by Credit or Debit Card
Major private hospitals in Indian metropolitan areas may accept international payment cards, but card-network acceptance, limits and authorization policies must be verified with the specific billing department. The patient's issuing bank may also restrict overseas transactions or require prior activation.
A card payment may involve merchant fees, issuer charges or currency conversion. Ask whether the terminal charges in INR or presents a foreign-currency alternative, and review the rate and fees before authorising.
The CDC Yellow Book's India chapter notes that many large hospitals accept major cards, but the same guidance cautions that payment methods vary by provider and location.
Should You Choose INR or Your Home Currency on a Card Terminal?
Some merchants or payment systems offer dynamic currency conversion, where the payment is displayed in the cardholder's home currency. The alternative may be settlement in the local currency, with conversion handled through the card issuer and network.
Neither choice can be declared cheaper for every card without knowing the offered rate and fee structure. Compare the displayed conversion, your card's foreign transaction terms and the final amount before confirming.
Keep the card receipt and bank statement. Do not assume that an exchange rate advertised elsewhere will match the rate used on the transaction.
Can Patients Pay Through an Online Payment Link?
Some institutions use online portals or payment links for registrations, consultations or deposits. Only use a portal that the hospital verifies through its official site or billing department.
Check the merchant name, currency, amount and service description before entering card details. If a payment link arrives unexpectedly or points to an unfamiliar domain, confirm it independently.
Do not disclose a card PIN, online banking password or one-time verification code to an individual claiming to be a hospital employee. Authorisation should occur through the legitimate payment workflow.
What About Cash Payments?
Hospitals may have rules concerning accepted cash amounts, identity verification and documentation. Applicable Indian tax, cash-transaction and foreign-exchange regulations can affect what is permissible.
It is not responsible to publish a universal cash limit for all patients and payment situations without checking current law and the exact transaction. Ask the hospital's accounts department and a qualified financial adviser where needed.
For significant treatment expenses, a documented bank or card payment can provide clearer records, though the patient should choose an appropriate lawful method.
Currency Exchange in India
International visitors may need Indian rupees for transport, accommodation and everyday expenses. The Reserve Bank of India regulates authorised foreign-exchange dealing and money-changing activities under FEMA and related directions.
Use banks or authorised money changers, request the applicable rate and fees, and retain the transaction receipt. Avoid informal exchanges with strangers offering unusually attractive rates.
The RBI's Master Direction on Money Changing Activities sets out the framework for authorised participants. For individual situations, ask a bank or qualified adviser about applicable documentation and limits.
Can a Family Member Pay on Behalf of the Patient?
Hospitals may accept payment from a relative, sponsor or another lawful payer subject to their billing and verification policies. The hospital may need the patient reference and details of the person funding treatment.
International remittances can also be subject to the sending country's banking and compliance requirements. The payer should ask the bank what supporting documents are required and ensure the invoice or receipt properly identifies the transaction.
Payment authority is not the same as authority to consent to medical treatment or access clinical records. Those roles should remain clearly documented.
NRIs, Overseas Residents and International Visitors
An NRI paying for a relative in India may use different lawful account and transfer arrangements from a foreign national paying for their own procedure. The availability and treatment of NRE, NRO or foreign-bank transfers depends on account rules, residency and transaction type.
Do not assume one account category is appropriate for everyone. The RBI's foreign-exchange and deposit guidance is relevant background, but individual remittance arrangements should be confirmed with an authorised bank.
A hospital's financial staff can explain how it accepts funds; the patient's bank or adviser should explain account eligibility and cross-border transfer compliance.
How Payment Rules Differ From the Sending Country
The legal and banking conditions for an overseas transfer may depend on where the payer lives, the bank used, sanctions screening, identity requirements and local capital or foreign-exchange controls.
A hospital in India cannot waive the sending bank's requirements. Patients should allow time for compliance checks and avoid assuming funds can reach the hospital immediately after a transfer is initiated.
If a payment is unusually large or complex, request written bank guidance well before the admission date. Never use an unverified third party to evade payment restrictions.
How Insurance Changes the Process
Some patients have coverage that permits planned overseas medical care, while others pay personally. Policies vary considerably and may restrict medical tourism, specific hospitals, treatment categories, follow-up or complications.
The CDC's travel insurance guidance notes that people receiving care abroad are often asked to pay first and then seek reimbursement. Do not assume the existence of health or travel insurance means the hospital will bill the insurer directly.
Contact the insurer in advance about preauthorisation, exclusions, network requirements, cashless arrangements and the exact reimbursement documents required.
Cashless Billing and Third-Party Administrators
Where a hospital has an eligible direct-billing arrangement with an insurer or third-party administrator, the patient may not need to advance every covered charge. Whether this is available depends on the policy, provider and authorised approval.
Ask for written confirmation of which services are approved, any co-payment, deposit or excluded charges and what occurs if treatment changes.
A preliminary coverage discussion is not the same as a guarantee of payment. The insurer or relevant administrator must confirm the actual authorisation.
When an Employer or Government Sponsor Is Paying
Some international patients have an employer, government programme or other sponsor funding treatment. In these cases, the hospital may require a letter of guarantee, approved estimate or formal payment authorisation.
The sponsor should explain its spending limits and which costs it covers. Flights, accommodation, additional treatment and attendant expenses may be outside the approval.
Keep the sponsor's approval separate from the hospital's clinical recommendations and final invoice. A sponsoring organisation cannot automatically override medical consent or treatment decisions.
Hospital Deposits and Insurance Can Overlap
Even when coverage is expected, a hospital may request an advance if preauthorisation has not yet been completed or if some charges are excluded. The precise process depends on the hospital and policy.
Ask how a deposit will be reconciled if the insurer later settles some or all of the bill. Clarify who receives any resulting refund and what supporting documents are needed.
Retain proof of each payment and the insurer's authorisation. The family should be able to trace every major amount to an invoice or statement.
During Treatment: Interim Billing and Additional Advances
Some hospitals issue interim bills during longer inpatient stays or request an additional advance when charges exceed the original deposit. This does not necessarily indicate wrongdoing; clinical needs and billing arrangements can change.
Ask for an itemised or sufficiently detailed update, the available deposit balance, the reason for additional charges and a named billing contact.
If the clinical plan changes significantly, request an appropriate discussion with the treating team as well as updated financial information. An administrative coordinator cannot substitute for clinical explanation.
What Happens at Discharge?
Before leaving hospital, the billing department may prepare a final statement showing the services provided, amounts charged, previous deposits, insurer payments and the remaining amount payable or refundable.
Review patient identifiers, dates, room charges, major procedures, medicines and any significant new items. Ask about discrepancies before finalising settlement, and retain the official itemised invoice and receipts.
Clinical discharge depends on the treating team. Payment clearance is an administrative process, and neither should be used to imply the patient is automatically fit to fly home.
Getting Copies of Invoices and Receipts
International patients should retain the estimate, deposit confirmations, official invoice, payment receipts, discharge summary and any refund or reimbursement correspondence. These documents support future queries and insurance claims.
Ask whether invoices can be provided electronically and whether translations or specific fields are needed by an overseas insurer. The hospital may be able to provide relevant documents but should not be assumed to satisfy every country's tax or insurance format.
The guide to returning home after treatment covers the broader discharge-document package.
What if the Final Bill Is Lower Than the Deposit?
Where the total billed amount is lower than the advance held, the hospital's refund process and the original payment arrangement determine how the balance is returned. It may require account verification, supporting documents or additional processing time.
For overseas refunds, currency conversion and bank charges can affect the amount credited in the payer's home currency. Ask whether the hospital refunds in INR or another currency, and who bears relevant costs.
Do not assume a refund will reproduce the original foreign-currency amount, especially if exchange rates have moved.
Refunds for Cancelled or Postponed Treatment
If a visit is cancelled because a visa was refused, the patient became unwell, or a clinician changed the plan, the hospital's terms govern the deposit and cancellation process, subject to applicable law.
Ask whether consultation fees, confirmed bookings or purchased supplies are refundable and whether a deposit can be applied to a rescheduled date. Written conditions are preferable to verbal promises.
A facilitator's coordination fee may have separate cancellation rules from the hospital's clinical deposit. Patients should not confuse the two.
What if the Card or Account Used for Payment Is Closed?
Refund processing can be more complicated if the original card is cancelled or bank account has changed. Contact the hospital's billing department and the financial institution that processed the payment.
The hospital may need to verify ownership and permitted refund routes. Never accept a request from a stranger to provide banking passwords or one-time codes as a supposed refund requirement.
Keep a dated record of the refund request and follow up through verified official channels.
Can a Facilitator Collect Hospital Payments?
Some coordinators may have a documented arrangement to facilitate or collect certain payments, but families should never assume such authority solely because an organisation introduced them to a hospital.
Ask the hospital to confirm who may collect its fees, the beneficiary, the invoice, and what portion—if any—belongs to the facilitator. A separate coordination invoice should clearly describe the services it pays for.
Carehorizon's guide to hospital direct versus facilitator routes explains why these responsibilities should remain transparent.
Keep Clinical and Coordination Costs Separate
Hospital treatment charges relate to medical care provided by the clinical institution. A facilitator's fees relate to stated administrative or travel coordination services. Third-party flights, accommodation and ground transport may be paid to other organisations.
A combined budget may be convenient, but families need a clear breakdown of the responsible entities. Ask who invoices, who receives payment, and which organisation handles cancellation or refund issues.
The guide to managing money and payments during treatment in India offers additional questions about documenting non-hospital expenses.
Do Not Forget Accommodation and Attendant Expenses
Hospital estimates generally should not be assumed to include hotels, serviced accommodation, food, local transport, visa fees or expenses incurred by accompanying family members.
Recovery may take longer than the predicted inpatient stay. Flexible accommodation and flight arrangements can help reduce the financial pressure to travel before clinical clearance.
The guide to staying near the hospital explains what families can consider when planning lodging around ongoing appointments.
Currency Conversion for Daily Expenses
Hospital costs may form the largest component, but smaller payments made in India also add up. Foreign card fees, ATM charges, cash exchange spreads and transport costs may affect the overall budget.
Rather than relying on one exchange rate for the entire journey, track the actual converted amounts when transactions occur. Note whether a bill is in INR and which account was charged.
A simple expense log separating medical, travel, accommodation and other costs makes the final settlement easier to review.
How to Build a Practical Payment Plan
Start with the written hospital estimate, then list the requested deposit, due dates and payment channels. Include possible additional charges based on the hospital's stated exclusions, without inventing a universal contingency percentage.
Add flights, accommodation, attendant costs and follow-up. Identify which expenses are fixed, which are changeable and which depend on clinical findings.
Before travel, make sure the bank or card provider can support the expected transaction amounts and that the hospital has a verified method for acknowledging incoming funds.
A Family Example: Paying by International Bank Transfer
Suppose a patient receives a hospital estimate and is asked to remit a deposit to the institution's bank account. The family verifies the beneficiary by independently calling the hospital's published billing number.
It then checks the required currency, bank transfer charges and patient reference. When the transfer is initiated, the family retains the bank receipt and waits for the hospital's confirmation of funds credited.
This hypothetical sequence illustrates good records and verification. It does not represent a guarantee that all hospitals accept overseas wires or that a transfer will settle on a fixed date.
A Family Example: Card Payment at Admission
Another international patient arrives for a consultation at a large hospital that confirms acceptance of the patient's payment card. The bank authorises a local-currency charge, and the patient retains the hospital receipt and card record.
If further treatment is recommended, the hospital provides a separate estimate and explains whether an advance will be needed. The family reviews the new plan before deciding how to pay.
The example demonstrates why a consultation charge, treatment deposit and final invoice should be recorded separately.
A Family Example: Insurer Approval Is Still Pending
Imagine a patient whose insurer is considering the proposed treatment but has not yet issued authorisation. The hospital explains its self-pay deposit policy and how any later insurer settlement might affect the account.
The patient contacts the insurer directly to clarify preauthorisation, covered services and whether reimbursement will occur after paying personally.
No one should promise cashless treatment until the relevant payer and hospital confirm the arrangement in writing.
Warning Signs in Medical Payments
Be cautious when a supposed hospital representative requests money to an unfamiliar personal account, changes bank details without explanation or insists on immediate payment without an official invoice.
Other warning signs include guarantees of a cure, an unexplained 'all-inclusive' fee, requests for banking passwords or one-time security codes, and refusals to identify the actual hospital billing entity.
A warning sign is a reason to investigate, not automatic proof of fraud. Verify all sensitive instructions through the hospital's independently sourced official contact information.
What to Do If You Sent Money to the Wrong Recipient
Contact the sending bank or payment provider immediately and ask what tracing, dispute or recall options may be available. Preserve the transaction reference, payment instructions and communications.
If financial cybercrime involving India is suspected, the Government of India's National Cyber Crime Reporting Portal provides reporting channels. Local law enforcement and the payer's home-country authorities may also be relevant.
Recovery is not guaranteed, and rapid action is important. Do not pay another unknown party who promises to recover funds for an advance fee.
How to Resolve a Hospital Billing Disagreement
Request the itemised statement and ask the billing department to explain disputed items against the written estimate, the actual clinical services and the relevant contract terms.
Keep the conversation focused on the specific amounts, dates and documents. If the concern involves a clinical change, request an explanation from the responsible treating professional rather than asking a billing administrator to justify treatment.
Escalate through the hospital's published grievance process if needed and seek appropriate professional advice for unresolved contractual or regulatory questions.
A Pre-Payment Verification Checklist
Confirm the hospital's exact identity and campus, the named beneficiary, the service being paid for and the official invoice or deposit request.
Check the currency, accepted payment method, bank or card fees, exchange-rate implications, transaction limits and how the payment will be acknowledged. Confirm the deposit's cancellation and refund terms.
Keep copies of the clinical estimate, payment instruction and receipts. Distinguish the hospital's charges from any coordination, accommodation or transportation fees.
Questions to Ask the Hospital Billing Department
Is the estimate in Indian rupees or another currency? Which payment methods are accepted from my country? Can I pay in advance by verified international transfer or through a secure payment portal?
What deposit is required, which parts are refundable and what is the estimated payment schedule? Are foreign bank or card charges included, and how will any short payment be handled?
Will I receive an itemised final invoice? How are additional tests, complications and longer stays billed? How will refunds be returned to an overseas payer?
Questions to Ask Your Bank or Card Provider
Can this account send the intended payment to an Indian hospital? What supporting documentation, beneficiary details, compliance checks or transfer limits apply?
Which currency conversion rate and fees will be used, and can intermediary-bank deductions occur? How can I trace a delayed wire? Does my card permit international hospital transactions at the required amount?
For refunds, ask how foreign-currency credits are handled and whether bank or card fees may be retained. Obtain answers from the provider actually processing the transaction.
How Carehorizon Health Supports Payment-Related Coordination
Carehorizon Health Private Limited coordinates the practical journey around clinical care. Depending on the enquiry, it may help families organise treatment documents, communicate with the hospital's billing contacts, track quotation questions and align travel planning with proposed appointments.
Hospitals set and collect their own medical charges under their applicable arrangements; banks and payment providers determine transaction processing; insurers decide coverage; and qualified clinicians determine treatment. Carehorizon does not guarantee hospital prices, payment approval, currency rates or refunds. Read how Carehorizon works for an overview of its coordination role.
For a planned international patient enquiry, use the Carehorizon enquiry page, call +91 6292041222 or email care@carehorizonhealth.com. Verify every invoice and payment instruction directly with the responsible provider before sending funds.
Frequently Asked Questions
How do international patients usually pay hospitals in India?
Payment methods vary. Hospitals may accept verified bank transfers, cards, online portals or other lawful methods; confirm the precise options with the chosen institution.
Do hospitals in India require a deposit from international patients?
Some do, depending on the service and hospital policy. Ask for the amount, purpose, official receipt and cancellation or refund terms.
Are medical treatment quotes in INR or US dollars?
The quote and settlement currency depend on hospital policy. Confirm whether a foreign-currency figure is indicative and who determines the exchange rate.
Can I transfer money from my home country to an Indian hospital?
Some hospitals accept overseas wires, subject to bank and regulatory requirements. Verify beneficiary details, fees and the hospital's preferred reference information.
Can I pay a hospital by international credit card?
Many large metropolitan hospitals accept major cards, but network acceptance, limits and fees must be confirmed before travel.
Will the hospital charge the exchange rate I see online?
Not necessarily. Banks and payment providers may apply different executable rates, fees and spreads. Ask how the payment will be converted.
Is a hospital treatment estimate a fixed bill?
Usually not unless defined contractual terms say otherwise. The final cost can change with actual investigations, care or recovery.
Will international health insurance pay the hospital directly?
That depends on the policy and provider agreement. Some patients must pay upfront and apply for reimbursement; seek written preauthorisation.
What happens if I cancel surgery after paying a deposit?
Refundability depends on the hospital's actual agreement and applicable rules. Request written cancellation terms before paying.
Can a medical tourism facilitator collect my hospital fees?
Only rely on such an arrangement after checking the coordinator's documented authority and the hospital's confirmation of the payee and invoice.
Official References and Further Reading
- CDC Yellow Book 2026 — Medical Tourism and Treatment Cost Inclusions: https://www.cdc.gov/yellow-book/hcp/health-care-abroad/medical-tourism.html
- CDC Yellow Book 2026 — India: Healthcare Access and Payment Cards: https://www.cdc.gov/yellow-book/hcp/asia/india.html
- CDC Yellow Book 2026 — Travel Insurance and Overseas Medical Expenses: https://www.cdc.gov/yellow-book/hcp/health-care-abroad/travel-insurance.html
- Reserve Bank of India — Master Direction: Money Changing Activities (updated September 29, 2026): https://www.rbi.org.in/scripts/BS_ViewMasDirections.aspx?id=11518
- Reserve Bank of India — FAQ: Miscellaneous Forex Facilities (updated November 28, 2025): https://rbi.org.in/scripts/FAQDisplay.aspx?Id=66
- Reserve Bank of India — Foreign Exchange Management (Deposit) Regulations: https://www.rbi.org.in/scripts/BS_ViewMasterDirections.aspx?id=10193
Medical, financial, banking and publication disclaimer: This article is general education, not a binding hospital quote, financial advice, legal interpretation of FEMA, bank-transfer instruction, exchange-rate guarantee, insurance confirmation or medical advice. Policies, rates and regulations may change and depend on the patient's circumstances. Verify hospital terms with the actual provider and banking or foreign-exchange requirements with an authorised institution. Qualified clinicians determine treatment, not financial coordinators. Internal Carehorizon website links were selected from the supplied inventory and require live-page verification before publication.
Carehorizon Health coordinates medical travel, patient transfers and related arrangements. The information here is educational; it does not diagnose, prescribe, guarantee an outcome or replace advice from your treating medical team. Service availability, costs and travel requirements are confirmed case by case.