This article provides general information to support better planning. Individual medical decisions and fitness for travel require assessment by qualified treating professionals.
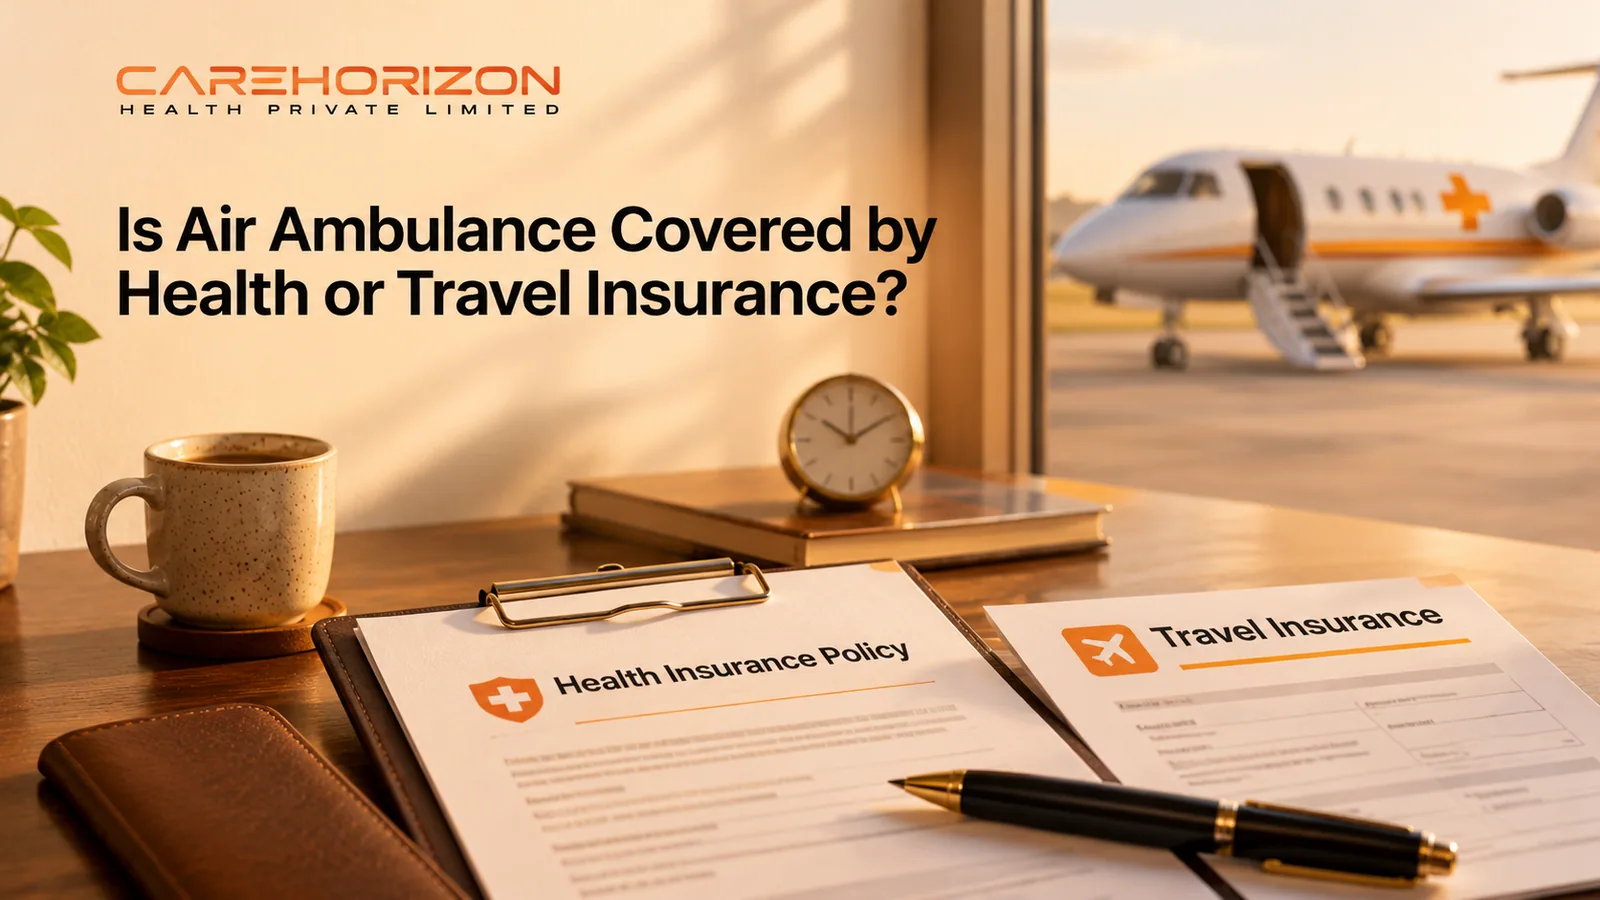
An air ambulance may be covered by health insurance or travel insurance, but coverage is not automatic. The answer depends on the exact policy, the patient’s condition, the reason for the transfer, where the journey begins and ends, whether the insurer considers it medically necessary, and whether its approval process has been followed. Some Indian health plans offer domestic emergency air ambulance benefits; some travel plans include medical evacuation or repatriation. Their conditions can be significantly different.
A family might have hospitalisation insurance and still discover that an interhospital transfer is excluded. Another policy may pay only for air evacuation to the nearest hospital with adequate emergency facilities, not to a hospital chosen for convenience. A travel assistance benefit may allow the insurer or assistance company to select a commercial flight with medical escort rather than a dedicated aircraft.
This guide explains what to check before arranging an expensive transport, how to compare cashless and reimbursement pathways, and what documents may be necessary. Carehorizon's air ambulance service overview explains the logistics that an insurance decision must account for.
The Short Answer: Coverage Is Possible, but Policy Wording Controls
Some Indian health insurance products expressly include air ambulance cover, often subject to emergency, medical-necessity, geography, maximum payment and transport-mode requirements. Other products omit it or offer it as an optional benefit.
Travel insurance can cover medically necessary evacuation while travelling or repatriation under specified circumstances. It may involve a 24-hour assistance service that helps arrange transport and determines the suitable mode with medical input.
Neither a doctor's recommendation nor possession of a large sum insured proves the air ambulance bill will be accepted. Families must read the applicable policy wording, schedule, endorsements and Customer Information Sheet, and seek case-specific confirmation.
Health Insurance vs Travel Insurance: What Is Different?
Indian health insurance
A health policy primarily protects against eligible healthcare expenses and may include ambulance benefits. The wording might permit emergency air evacuation within India but restrict the destination to the nearest suitable hospital or tie payment to an admissible hospitalisation claim.
For example, published ICICI Lombard Health Shield 360 wording describes an air ambulance benefit for a life-threatening medical emergency where road transportation cannot be provided, with limits and exclusions including hospital-to-hospital transfers and transport outside India. This example illustrates one policy's restrictions, not a rule for every Indian insurer.
Travel insurance
Travel insurance generally focuses on events occurring during a covered trip. Its medical evacuation or assistance benefits may have their own limits, covered geographic regions, trip-duration restrictions, medical-condition exclusions and requirements to call the assistance provider.
Published Tata AIG travel insurance wording describes an assistance-company medical panel assessing whether evacuation is appropriate and selecting the mode, which may include an air ambulance, a regular airplane or another suitable method. A family should not assume that a private air ambulance booked independently will be reimbursed.
Employer, group and specialist policies
Employer group health cover, corporate travel plans and specialist international medical policies can have different rules from retail products. Some arrangements include assistance services or add-ons. Check the insured member's certificate and the actual master policy, not a generic description of the insurer's brand.
1. Is Air Ambulance Cover Actually Included in Your Policy?
Look for headings such as Air Ambulance, Emergency Medical Evacuation, Medical Transportation, Medical Repatriation, Emergency Assistance or Ambulance Benefit. A policy that mentions 'ambulance charges' may refer only to road transport.
Check whether the benefit is part of the basic policy, an optional rider or an additional cover selected at purchase. If a rider was never purchased, a description of that rider on the insurer's website does not establish coverage.
Obtain the policy schedule and policy wording for the exact product and version. Product brochures and comparison pages can summarise benefits, but the applicable contract and endorsements define the conditions.
2. Is the Transport Medically Necessary Under the Policy?
Medical necessity is a key condition in many air evacuation benefits. The policy may require a medical practitioner's written recommendation and evidence that urgent care could not reasonably be reached through ordinary ground transport. Some policies also require the insurer's or assistance provider's own medical assessment.
A patient can be seriously ill without satisfying a narrowly drafted emergency transport benefit. For instance, a family preference to shift hospitals closer to home may be understandable but different from an insured emergency evacuation to the nearest facility capable of treatment.
Ask the treating team to document why transfer is required, what treatment is unavailable locally, and why the proposed transport mode is appropriate. The guide to fitness-to-fly assessments provides related medical context.
3. Is the Journey Within India or International?
Geographic restrictions are crucial. Some Indian health plans cover emergency air ambulance only when both the incident and treatment occur in India. The existence of worldwide hospitalisation cover in a broader plan does not automatically mean an international medical flight is covered.
An international travel policy may provide emergency medical evacuation from a foreign country or medical repatriation to India, depending on the wording. Coverage can also depend on the trip purpose, departure date, region and maximum covered travel duration.
For cross-border journeys, see the international air ambulance pathway to understand why aviation permits, travel documents and receiving-care arrangements may need separate consideration.
4. Emergency Evacuation vs Hospital-to-Hospital Transfer
Many families use the expressions interchangeably, but insurers may not. Emergency evacuation can mean taking someone from the site of a medical emergency to the nearest facility with suitable care. Interhospital transfer means moving from one hospital to another, perhaps because specialist treatment is needed.
Some benefits explicitly exclude transfers between hospitals, even where the patient remains critically ill. Others permit particular medically necessary transfers if the current facility cannot provide required treatment. The policy must be checked rather than assuming that all urgent transfers qualify.
Make the proposed starting point, destination, medical indication and existing hospital capability clear when requesting written insurer approval.
5. Does the Policy Require the Nearest Suitable Hospital?
Some air ambulance policies restrict cover to the nearest hospital with adequate emergency facilities. This may differ from the hospital the family prefers or where a treating specialist is based.
The insurer may assess whether capable care exists nearer to the patient. A long flight to a distant city could be clinically justified yet fail a particular insurance condition if a nearer suitable option was available.
Ask the insurer to identify the destination rule and what medical evidence would support an exception, if one exists in the contract. Do not book a longer route on the assumption that a doctor’s letter always overrides that clause.
6. Is Prior Approval or Insurer-Arranged Transport Required?
Some policies require advance authorisation, notification or use of an approved assistance provider. In certain travel assistance products, reimbursement for independently arranged medical evacuation may be restricted unless the insurer or its authorised representative agrees.
Contact the insurer or assistance number as early as clinically appropriate. Provide the policy number, current condition, hospital details, recommended transfer, destination and proposed mode. Request written clarification of what is approved.
A genuinely urgent clinical decision may not allow lengthy administrative preparation. Families should still preserve records of attempts to notify the insurer and ask about the applicable emergency-intimation procedure. Necessary medical care should not be delayed solely to secure a non-clinical promise of reimbursement.
7. Does the Plan Pay Cashless or Through Reimbursement?
Cashless arrangements
Cashless means an insurer or its assistance provider makes an accepted direct-payment arrangement for specified services, under the applicable policy and provider arrangements. It is not a guarantee that every air ambulance supplier accepts direct settlement.
India's regulator has prescribed timelines for hospital cashless claim authorisation, but those hospital claim processes should not be assumed to create automatic cashless approval for every separately billed aircraft charter or medical evacuation.
Reimbursement
Reimbursement means the insured or another payer initially settles eligible costs and then submits a claim with supporting documents. It may apply when the transport company is outside a direct-billing arrangement or the policy expressly provides reimbursement.
A family should ask which costs require advance payment and whether the insurer has agreed in writing that those expenses fall within the benefit. Reimbursement is subject to eligibility, documents and policy limits, and may be partial or denied.
8. What Is the Air Ambulance Coverage Limit?
A policy may pay up to a fixed rupee amount, a percentage of the base sum insured, or a separate benefit maximum. It may apply per event, per hospitalisation or over the policy period.
For example, publicly filed Star Health policy wording describes an air ambulance reimbursement benefit with defined per-hospitalisation and annual limits; a separate older product wording sets a percentage of the base sum insured. These examples show why amounts cannot be generalised across products or versions.
A substantial hospitalisation sum insured does not mean the full aircraft cost is covered. Ask how the air ambulance limit interacts with deductibles, copayments and amounts already claimed under the policy.
9. What Exclusions Can Affect an Air Ambulance Claim?
Common policy-specific questions involve elective transfers, non-emergency travel, lack of documented medical necessity, transport to a non-eligible destination, treatment available locally, journey outside the geographic scope and independently arranged flights that bypass required approval.
Some policies exclude or restrict pre-existing-condition related events, certain activities, particular trip purposes or travel duration. Restrictions vary. Do not assume a claim is excluded merely because a patient has a pre-existing illness, or included because the patient needs an ICU.
Review the exclusions in the actual wording and request the insurer's written reasons if it says the proposed journey is not covered.
10. Is a Dedicated Air Ambulance the Only Insured Option?
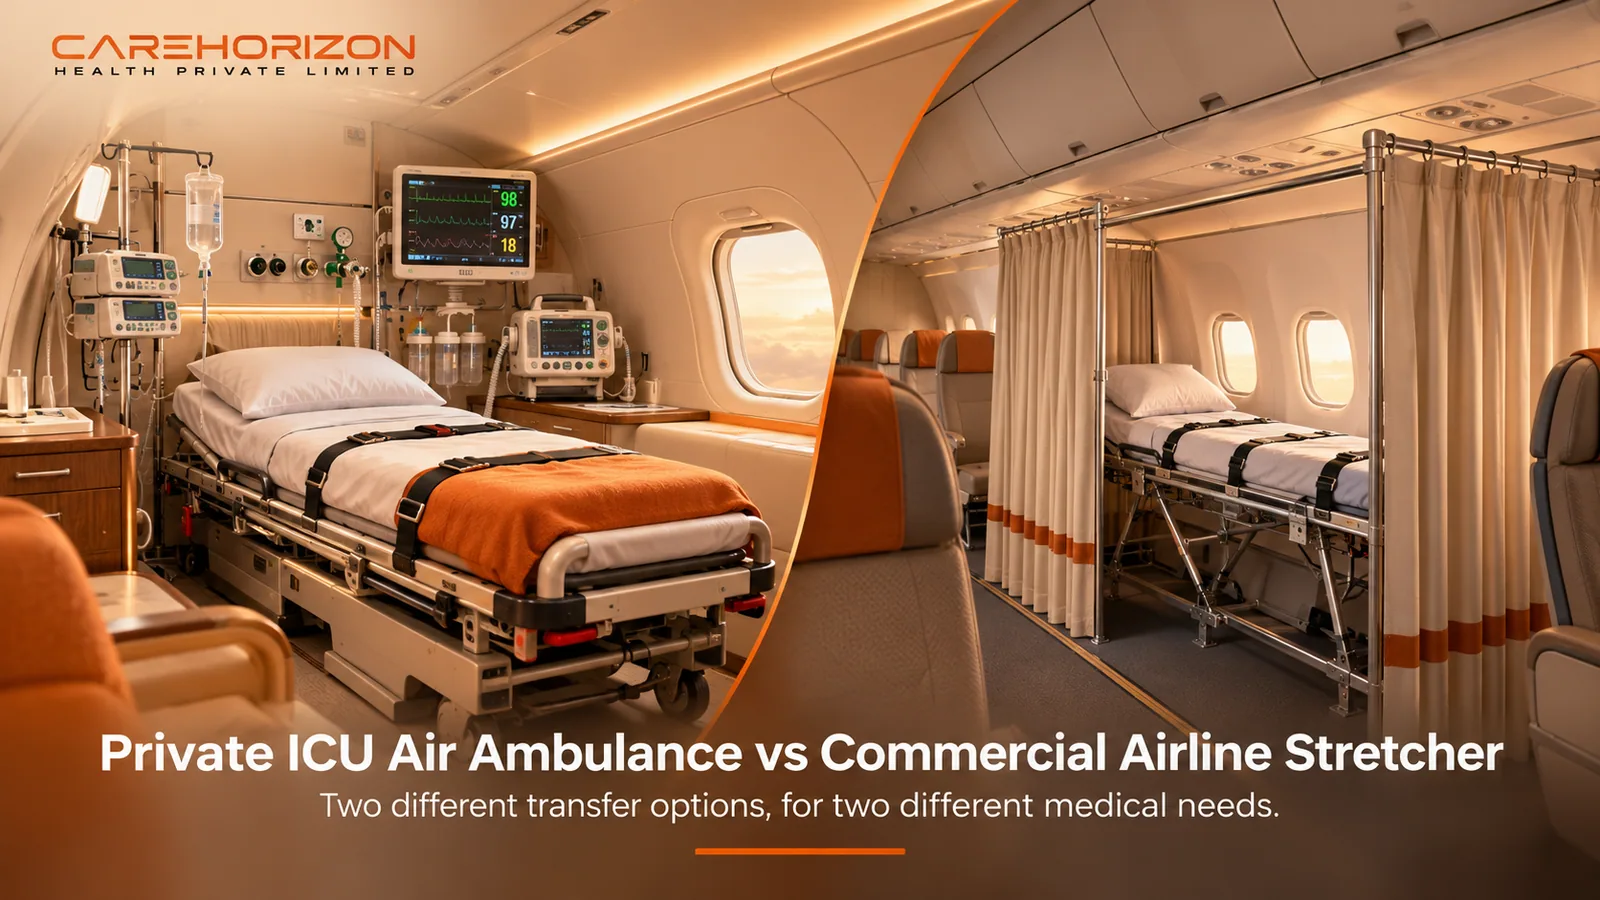
No. Depending on the patient's condition and policy terms, an assistance provider may consider a scheduled airline with a doctor or nurse escort, an airline stretcher, a ground ambulance or a dedicated medical aircraft.
The transport mode must be medically suitable and allowed by the carrier or operator. A less expensive airline arrangement is not interchangeable with critical-care transport for a patient who needs support the passenger cabin cannot provide.
The medical escort service page explains the difference between a scheduled-flight escort and a dedicated aircraft.
11. Are Ground Ambulances and Medical Escorts Included?
A complete bed-to-bed transfer often includes ground ambulances at departure and arrival airports, qualified medical staff, equipment, oxygen, handling arrangements and a final clinical handover. The insurance benefit may cover all, some or none of those components depending on its definitions.
Ask whether the benefit includes medical personnel, stretcher costs, airport handling, oxygen, aircraft positioning and both ground transport legs. A claim limit may also apply across the combined transport service rather than separately to each part.
Read the ground ambulance and airport coordination guide to understand why these stages should be itemised when requesting insurance approval.
12. What Documents Support an Air Ambulance Insurance Claim?
The insurer may request the policy and claim details, a current medical report, the treating physician's recommendation, evidence of medical necessity, admission and discharge records, relevant investigation reports and confirmation from the receiving hospital.
Transport documents may include an itemised quotation, invoice, receipts, aircraft or service details, medical team records where relevant, ground ambulance bills and evidence of the actual journey. For an international mission, travel and immigration documents may also be relevant.
Requirements differ. Request a current document checklist from the insurer or assistance provider and retain clear copies of records. The hospital-to-hospital transfer documents guide helps organise clinical information separately from insurance administration.
How to Seek Approval Before Booking
First, locate the exact insurance policy wording and any selected add-ons. Next, ask the treating clinician whether the transfer is medically appropriate and obtain the relevant medical summary and recommendation.
Then contact the insurer's claims or emergency assistance channel, explain why air transport is proposed and ask whether the plan covers this specific route and mode. Share the preliminary quote and the receiving hospital details through the designated secure process.
Ask for written confirmation of the insured benefit, any conditions, permitted provider, maximum liability, approved transport mode, whether it is cashless or reimbursable, and the claim reference number. Do not confuse acknowledgement of an enquiry with a final coverage decision.
What if the Insurer Cannot Approve the Flight Immediately?
If the patient requires urgent medical care, the treating clinical team should determine what action is necessary and safe. The insurance process and clinical decision are related but not identical.
Record the time and method of notifying the insurer, the reference number, any instructions and the documents supplied. Ask whether emergency retrospective review is contemplated by the specific policy, without assuming that it guarantees payment.
Where the family proceeds without confirmed coverage, it should understand the possibility of out-of-pocket cost and the potential for partial or unsuccessful reimbursement.
How to File a Reimbursement Claim After the Transfer
Notify the insurer within the applicable policy time limits, complete its required claim process and submit readable supporting documents. Include the treating clinician's rationale for air transport, service invoices, receipts, relevant hospital records and available correspondence about authorisation.
Keep an itemised account of transport charges and identify any amounts already covered by a direct settlement or another insurer. If the provider's invoice includes services not clearly listed in the policy, ask how those items will be evaluated.
Track the claim through the insurer's recognised channel and keep copies of acknowledgement, requests for additional information and the final decision. Avoid submitting inconsistent descriptions of the route or clinical purpose.
What if Insurance Covers Only Part of the Cost?
A partial payment can result from a benefit cap, deductible, copayment, excluded charges or a decision that only part of the journey qualifies. The insurer should explain the basis with reference to the policy.
Ask for an itemised settlement statement showing the eligible amount, reductions and the clause supporting each deduction. The remaining amount may be payable by the family or another responsible payer.
If another relevant policy exists, ask the insurers how the claims can be coordinated under the applicable terms rather than assuming the same expense can be reimbursed twice.
What if the Claim Is Rejected?
Request the insurer's written rejection with reference to the exact policy clauses and relevant facts. Check whether the denial concerns missing documents, medical necessity, geography, transport mode, pre-approval or another condition.
If information is incomplete or misunderstood, provide the additional medical explanation and request formal review through the insurer's grievance process. The insurer's own grievance redressal officer is an appropriate initial channel.
IRDAI's Bima Bharosa portal explains the escalation route if an insurer's response is unsatisfactory or the grievance remains unresolved. The Insurance Ombudsman may be another avenue where eligibility and procedural conditions are met.
How the IRDAI Grievance Process Works
IRDAI's Bima Bharosa FAQ advises policyholders to write to their insurer's grievance redressal officer and seek acknowledgement. It identifies a 15-day insurer response expectation and describes escalation to IRDAI when resolution is unsatisfactory or delayed.
The portal is designed to register and track complaints; it is not a mechanism that automatically confirms a disputed benefit as payable. An Insurance Ombudsman route may be available according to applicable jurisdiction, eligibility and procedural rules.
Official grievance information is available at https://bimabharosa.irdai.gov.in/Home/FAQ. Families should retain the claim decision, policy document, clinical records and correspondence if contesting the insurer's interpretation.
Domestic Emergency Air Ambulance: A Practical Example
Consider a hypothetical patient who becomes critically ill in a remote Indian location. The nearest appropriate hospital is beyond practical ground access, and the treating doctor recommends air evacuation. A policy with domestic emergency air ambulance cover may consider this type of situation, subject to its terms.
The insurer may still require evidence that road transport was unsuitable, that the destination was an eligible hospital and that the medical necessity was documented. A policy maximum can mean only part of the total mission cost is payable.
The example illustrates how coverage is assessed and is not an assurance that any named policy will reimburse a particular journey.
Interhospital Transfer: Why an ICU Referral May Still Be Excluded
Imagine a patient already admitted to a hospital whose family seeks transfer to another city for specialist treatment. Even if clinicians recommend transfer, a policy restricted to emergency evacuation from the incident site to the nearest eligible hospital may not cover this different journey.
Other policies or assistance agreements may permit clinically necessary interhospital movement. The distinction must be checked against the actual policy and documented clinical circumstances.
For the care-planning side, the guide to air ambulance transfers explains why sending and receiving hospital responsibilities must be confirmed independently of insurance.
International Medical Repatriation: What Families Must Check
A traveller hospitalised outside India may need medical assistance to return home. The policy's definitions of evacuation and repatriation, the covered destination, assistance-company authority, trip duration and medical-condition exclusions determine whether transport is covered.
Some travel assistance arrangements reserve the right to select the method and timing of travel based on clinical assessment. The family should not book a private air ambulance first and assume the assistance company will refund it later.
Carehorizon's guide to bringing a patient home to India from abroad explains the receiving-hospital, documents and ground-transfer planning behind such journeys.
Five Questions to Ask Your Insurer on the Phone
Ask: Does my exact policy and purchased add-on cover the proposed air ambulance journey? What medical necessity and destination conditions must be met? Do you require your assistance company to arrange or approve the transport?
Next ask: What is the maximum payable amount, and does it include medical crew, oxygen and ground ambulances? Will this be direct settlement or reimbursement, and what documents and notification deadlines apply?
Finally request a written response or documented claim reference. Notes from a call help, but cannot replace the actual policy and formal decision.
How Carehorizon Health Coordinates the Practical Journey
Carehorizon Health coordinates travel logistics around the patient's clinical care. For a potential air ambulance journey, that may involve helping families organise relevant medical records, clarify the transport pathway and align communication among sending and receiving hospitals, medical transport providers, aviation operators and ground teams.
The insurer or assistance provider determines coverage under the policy. Treating and transport clinicians determine medical suitability, while authorised operators manage aviation feasibility. Learn more about how Carehorizon works for the organisation's coordination role.
For an air ambulance enquiry, use Carehorizon's enquiry page, call +91 6292041222 or email care@carehorizonhealth.com. For an immediate medical emergency, seek local emergency medical attention rather than waiting for an insurance determination.
Frequently Asked Questions
Does every health insurance policy in India cover air ambulances?
No. Coverage may be included, optional or absent, and is governed by the exact policy wording and purchased benefits.
Can an air ambulance be covered for travel outside India?
Some travel or specialised international policies include medical evacuation or repatriation, while certain domestic health benefits are limited to India.
Is a doctor's recommendation enough for reimbursement?
Not necessarily. The policy may also require emergency conditions, specified destination, insurer authorisation and other terms.
Can I book any air ambulance and claim later?
Not safely assumed. Some policies or assistance services require use or approval of their designated provider and can restrict independently arranged transport.
Is air ambulance cover cashless?
Sometimes, if a direct-payment arrangement is approved and available. Other benefits require reimbursement after the insured pays the provider.
Does insurance cover an ICU-to-ICU air transfer?
Some policies may, but others specifically exclude interhospital transfers. Review the policy wording and obtain case-specific confirmation.
Does the insurer pay the full air ambulance bill?
Not always. Benefit caps, copayments, deductibles and exclusions may leave a balance payable by the family.
Are medical escorts and ground ambulances included?
Only if the policy terms or approved assistance arrangement include those services. Confirm the scope in writing.
What records are needed for reimbursement?
Common documents include the medical necessity report, patient and policy details, hospital records, the air ambulance invoice, receipts and insurer correspondence.
Where can I complain if my insurer rejects the claim?
Begin with the insurer's grievance officer. If unresolved or unsatisfactory, refer to IRDAI's Bima Bharosa guidance and assess Ombudsman eligibility.
Official Sources and Policy Examples
- IRDAI Bima Bharosa — Insurance Grievance FAQ: https://bimabharosa.irdai.gov.in/Home/FAQ
- Ministry of Finance / Press Information Bureau, 26 March 2026 — Cashless Health Insurance Claim Timelines: https://www.pib.gov.in/newsite/erelcontent.aspx?lang=2®=48&relid=286915
- ICICI Lombard Health Shield 360 — Air Ambulance Policy Wording (illustrative product, not a universal rule): https://www.icicilombard.com/docs/default-source/default-document-library/1345_hs360.pdf
- ICICI Lombard Health AdvantEdge — Domestic Air Ambulance Benefits Overview (verify current schedule): https://www.icicilombard.com/health-insurance/health-advantedge
- Tata AIG — Travel Insurance Asia Policy Wording 2026, Medical Evacuation and Assistance: https://www.tataaig.com/s3/tata_aig_travel_insurance_asia_policy_wordings_d211111f9b.pdf
- IRDAI Policyholder Portal — Published Health Policy Wording with Domestic/International Emergency Assistance: https://policyholder.gov.in/documents/37343/931203/ADIHLIP21061V022021_2020-2021.pdf/57e9f6ec-48f1-ad4a-e98e-4b6e947de35b?download=true
Insurance, clinical and publication disclaimer: General information only, not an insurance coverage opinion, financial recommendation or patient-specific medical clearance. Policy provisions, amounts, and regulations may change. Insurers and assistance providers interpret and decide coverage under the applicable terms; treating and transport clinicians assess patient suitability. Brand product descriptions here illustrate variation and are not endorsements. Carehorizon internal URLs are drawn from the supplied inventory and must be verified as live before publication.
Carehorizon Health coordinates medical travel, patient transfers and related arrangements. The information here is educational; it does not diagnose, prescribe, guarantee an outcome or replace advice from your treating medical team. Service availability, costs and travel requirements are confirmed case by case.